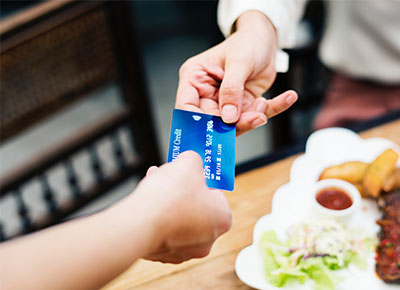
Recognize When to Reduce Your Credit Card Usage for Financial Health
Utilizing a credit card is a common practice that can enhance your shopping experience, provided you manage your payments wisely. Paying off your balance in full each month is crucial to avoid incurring interest charges, which can quickly diminish your financial health. Credit cards are advantageous as they often offer superior consumer protection compared to debit cards, allowing you to make purchases even when cash is not immediately available. However, the convenience they offer can lead to a false sense of security regarding your finances. If you’re facing challenges with credit card spending, consider consolidating your credit card debt to regain control of your financial situation while also adopting more responsible spending habits to secure long-term economic stability.
Identifying when to cut back on your credit card use is essential for maintaining financial well-being. Below, we discuss five key indicators that signal the need to reassess your credit card habits.
1. Inability to Recall Recent Purchases Made on Your Credit Card
Do you find yourself puzzled by the charges on your credit card statement each month? For instance, that seemingly overpriced £50 lunch last week—what exactly did you indulge in? Do you truly shop for new clothes every weekend without a plan? Such lapses in memory regarding your spending can indicate a deeper issue with your financial management. When confusion arises about what you’ve purchased, it suggests a disconnect between your spending patterns and your financial goals. Poor financial habits can accumulate over time, leading to significant trouble if not addressed. It’s essential to review your spending regularly and ensure you understand where your money is going to improve your financial awareness and control.
2. Difficulty Meeting Other Financial Obligations Due to Credit Card Spending
If you find it increasingly challenging to pay your essential bills, such as your gas bill or even more minor expenses like window cleaning, your credit card use might be a contributing factor. Many individuals rely on direct debits to pay off their credit card balances each month, which is generally a good practice. However, this can quickly become problematic if your credit card spending spirals out of control. Keeping a vigilant eye on your credit card balance is vital. By budgeting effectively and knowing your spending limits, you can ensure that you maintain sufficient funds for other bills while also leaving a buffer for unexpected expenses. Staying within your budget is critical for maintaining a healthy financial life.
3. Managing Multiple Debts with Your Credit Card
It’s not unusual for individuals to use credit cards to manage other debts, such as missed payments on loans or overdrafts. This practice merely transfers the debt rather than addressing the underlying financial issues. Relying on credit cards in this manner can lead to escalating problems if not properly managed. The cycle of using one debt to pay off another can become overwhelming and unsustainable. Luckily, options like a debt consolidation loan can simplify your finances by merging multiple debts into one manageable monthly payment. This approach can relieve stress and help you regain control over your finances if you find yourself juggling various debts without a clear strategy.
4. Feeling the Urge to Apply for Additional Credit Cards
Having multiple credit cards can be manageable for some, especially when balances are paid off consistently and spending remains within limits. However, if you’re feeling compelled to apply for another credit card without a clear rationale, it may indicate that you are struggling with your current card’s limits. Often, this desire stems from maxing out your existing card and seeking additional financial flexibility. This moment calls for caution—adding another card will likely lead to further debt accumulation and could result in high-interest charges on your current balance. Instead of succumbing to this temptation, focus on managing your existing credit card responsibly to prevent additional financial strain.
5. Anxiety About Parting with Your Credit Card
If you’ve recognized a problem with your credit card usage but find yourself unable to consider cutting it up, this may be the core of your financial difficulties. The convenience and accessibility of credit cards can become addictive, leading to an unhealthy reliance on them for everyday purchases. The thought of giving up your card may evoke anxiety, but it is essential to remember that doing so can pave the way to achieving a debt-free future. Embrace the opportunity to reassess your financial habits and make the necessary changes to improve your financial health. Take a moment to breathe and make the commitment to your economic well-being by taking control of your spending habits.
Assess Your Credit Card Habits for Better Financial Management
Credit cards can significantly enhance our personal financial management when used responsibly. However, it’s all too easy to slip into detrimental habits that can jeopardize our financial future. If any of the aforementioned signs resonate with you, it’s crucial to take a step back and evaluate your credit card usage. Making informed decisions about your spending will not only improve your current financial situation but also contribute to your long-term financial security.
Explore Related Articles That Can Benefit You:
 Starting Debt Consolidation With Bad Credit: A UK Guide
 County Court Judgments Explained: What You Need to Know
 Debt Consolidation Loan Credit Score Minimums: UK Guide
 Budget-Friendly Tips for a Festive Christmas
 Whether to Wait or Act on Debts Now: Essential Steps
 Common Misconceptions About Consolidation Loans: